Ενότητα για τους κατασκευαστές γενικά
Άβαταρ μέλους
By dimik
#898583
PaNick67 έγραψε:To Kia ev3 είναι απείρως πρακτικοτερο από το ΜΥ, φθηνότερο και με διαστάσεις που ταιριάζουν στην πόλη.
Ας έχει 200 άλογα "μόνο".
Αυτά είναι λίγο και περί ορέξεως.

Το point μου ήταν ότι υπάρχουν ηλεκτρικά με αντίστοιχο ή και καλύτερο εξοπλισμό σε χαμηλότερη τιμή.


< >
Άβαταρ μέλους
By Serf
#903611 Εικόνα

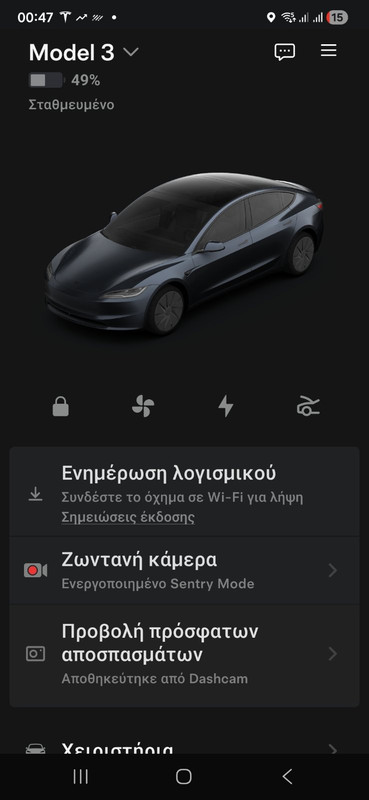
Model 3 Standard Range του '26 (μέσω leasing) προς αντικατάσταση του Model 3 Standard Range του '24 :inlove:

Και παραμένει (για λίγο ακόμα) βασικό της οικογένειας το Model Y Performance του '24.
Άβαταρ μέλους
By PaNick67
#903617 Καλοριζικο! ( δεν βαρεθηκατε 2+ χρονια το ιδιο αμαξι και το πηρατε ξανα; )

Μετα το Υ Performance τι ακολουθει;
Άβαταρ μέλους
By edmond
#903619 Τεζλαίος όνομα και πράγμα :lol:
Καλορίζικο :s_roses
Άβαταρ μέλους
By BARHonda
#903966 https://x.com/gnoble79/status/2047416199122973107

Last night was the biggest disaster in the history of Tesla.

Let me walk you through what actually happened on that earnings call, because the headlines are doing you a disservice:

Elon Musk got on the call and admitted (his words) that Hardware 3 "simply does not have the capability to achieve unsupervised FSD."

He said he wished it were otherwise. He said the memory bandwidth is one-eighth of what Hardware 4 has. And that's the end of the conversation.

Approximately 4 million Tesla vehicles on the road right now have Hardware 3. Many of those owners paid $8,000 to $15,000 for Full Self-Driving capability based on Musk's repeated promises (going back to 2016) that the hardware was sufficient for full autonomy. As recently as 2022, Musk was publicly assuring owners that HW3 had the processing power to get it done.

BUT IT DIDN'T

Those promises are now officially broken.

The solution is a "discounted trade-in" toward a new car with Hardware 4.

Not a refund or a free upgrade...
A discount on buying ANOTHER Tesla.

Investor Ross Gerber said it too - all HW3 owners got screwed, and with roughly 285,000 FSD purchasers affected, the potential liability runs into the BILLIONS.

But that's not even the worst part.

Musk was asked if the current FSD v14.3 was ready for unsupervised deployment. He said yes. Then immediately walked it back and admitted Tesla has "major architectural improvements" in the pipeline that would significantly improve safety.

What he really means: the software isn't SAFE ENOUGH to deploy without a human watching. Full unsupervised FSD for consumer cars is pushed to Q4 2026. At the earliest... Maybe.

How many times has this deadline been pushed? I've lost count. And trust me, I've seen a lot of broken promises. But this one takes the cake.

Now let's talk about the numbers everyone is celebrating:

Tesla reported $22.4 billion in revenue and $0.41 in non-GAAP earnings. A "double beat." The stock popped 4% after hours. Victory, right?

WRONG

Dig into the actual filing:

The number one driver of operating income improvement wasn't cost reductions, wasn't volume growth, wasn't FSD revenue. It was - and Tesla listed this FIRST in their own shareholder letter - "one-time benefits related to warranty and tariffs."

They released warranty reserves. They booked tariff refund windfalls. They stretched supplier payments by 10 days. They took on billions in new debt. Then they presented everything through non-GAAP metrics that strip out over $1 billion in stock-based compensation.

GAAP net income was $477 million on $22.4 billion in revenue. That's a 2.1% net margin. On a $1.4 trillion market cap.

Let me put that in perspective:

3.75 billion shares outstanding. Annualize the Q1 GAAP profit and you get roughly $1.9 billion. That's a trailing P/E ratio north of 700. Use the adjusted number - strip out stock comp, which is a REAL cost to shareholders through dilution - and you're still at around 250x earnings.

All of this is extremely bad, but I didn't even talk about the CAPEX BOMB yet...

3 months ago, Tesla guided to "over $20 billion" in 2026 capital expenditure. Last night they raised it to over $25 billion. A $5 billion increase in a single quarter. That's 3x their historical annual capex run rate - $8.5 billion in 2025, $11.3 billion in 2024. The CFO confirmed on the call that Tesla expects NEGATIVE free cash flow for the rest of the year.

So you have a company generating roughly $6 billion in annual free cash flow on a good year, and they're about to spend $25 billion.

The math doesn't work.

They will almost certainly need to issue equity. Which means dilution. Which means the $1.9 billion in annual earnings gets spread across even MORE shares.

The core auto business is literally deteriorating in real time:

Tesla delivered 358,000 vehicles in Q1 (missed estimates again).

They produced 408,000. That's 50,000 cars sitting on lots that nobody bought.

Inventory days jumped from 10 to 27 in just a few quarters. California (their most important US market) saw registrations crash 24% year over year.

Their market share in the state fell from 9.2% to 7.7%. That's on top of a Q1 2025 that was ALREADY weak from Model Y retooling. They're declining off a decline.

And here's what really kills the bull case...

The entire valuation rests on robotaxis, Optimus robots, and autonomy. So let's put numbers on it:

Waymo - the actual leader in autonomous driving with 15 million completed rides in 2025 alone, over 127 million autonomous miles driven, operating commercially across 6 US cities with plans to expand to 20 more - just raised $16 billion at a $126 billion valuation.

That's the market's verdict on what the LEADING robotaxi company is worth. $126 billion.

And Waymo is YEARS ahead of Tesla in actual deployment.

Tesla has 3.75 billion shares outstanding. So even if you assign $126 billion in robotaxi value (giving Tesla full credit for matching Waymo despite being nowhere close) that's $33 a share. Add the auto business at generous auto-industry multiples, maybe $20 a share. Throw in energy storage and services, $10-15.

Sum of the parts gets you to roughly $65-70 a share if you're feeling generous. Maybe $50 if you're not.

The stock is $387.

So what exactly are you paying for?

You're paying for a STORY. You're paying for PROMISES that keep getting pushed back, technology that keeps falling short, and a business plan that requires spending $25 billion a year while the core product sells fewer units at declining margins in a market where California sales just fell 24% and the federal EV tax credit is gone.

I managed the number one mutual fund in America. I founded two billion-dollar hedge funds. I've been doing this since 1981.

And I am telling you:

Tesla at $387 is one of the most egregious mispricings I have seen in my entire career.

THE CRASH WILL BE EPIC


Και περιμένω σχόλιο markvag "Σας τα λέω χρόνια"

Εν τω μεταξύ κάνει μπαμ ότι το κείμενο είναι γραμμένο με AI, έχω βαρεθεί να διαβάζω ποστ που είναι δομημένα έτσι
Άβαταρ μέλους
By markvag
#903974
BARHonda έγραψε:https://x.com/gnoble79/status/2047416199122973107

Και περιμένω σχόλιο markvag "Σας τα λέω χρόνια"


:lol: :lol: :lol:

΄συ είπας :shifty: :shifty: :shifty: :s_biggrin :s_biggrin
Άβαταρ μέλους
By NirApp
#903985 H Tesla δεν εχει ανταγωνιστικο προιον, η Κινα την εφτασε και την ξεπερασε.
Άβαταρ μέλους
By BARHonda
#903986 Κατ’εμέ, σε σύγκριση με τους Ευρωπαίους κατασκευαστές είναι χαλαρά 1η. Η Κίνα είναι άλλο φρούτο
Άβαταρ μέλους
By Isambard
#903997 Η Tesla πουλάει μια χαρά και στην Κίνα, ακόμη τουλάχιστον, άρα ακόμη έχει ανταγωνιστικό προϊόν. Το Y είναι πρώτο στην κατηγορία του και στην πρώτη πεντάδα των EV.
Το πρόβλημα εκεί πως η Tesla δεν εχει ανακοινώσει νέα μοντέλα και δεν φαίνεται να μπορεί να αντισταθεί και αυτή στην ορμή των Κινέζων, οι οποίοι έχουν επενδύσει και στην αυτόνομη οδήγηση και ειδικά η Huawei είναι πολύ δυνατή και πουλάει και την τεχνολογία της σε άλλους όπως στην BYD.
Οι Ευρωπαίοι δεν έχουν καμία ελπίδα, θα αντέξουν κάποια χρόνια με δασμούς ίσως και μετά θα συμβεί ό,τι συνέβη στην Αγγλική αυτοκινητιστική βιομηχανία : θα κλείσουν ή θα εξαγοραστούν.
Δείτε τι γίνεται στην Κίνα που χάνουν διαρκώς μερίδιο, απλώς δεν είναι πλέον ανταγωνιστικά τα προϊόντα τους.
Άβαταρ μέλους
By Serf
#904002 Η Tesla έχει δύο βασικά μειονεκτήματα σε σχέση με τον κινέζικο (και όχι μόνο) ανταγωνισμό:
- Έλλειψη πρότασης/προτάσεων σε μικρότερες κατηγορίες
- Μη εξέλιξη σε επίπεδο ταχύτητας φόρτισης... έχει "κολλήσει" στα 400V ενώ αρκετά νέα μοντέλα παίζουν με 800V και - κατά συνέπεια - αυξημένο άνω όριο ταχύτητας φόρτισης ή/ και αυξημένη καμπύλη φόρτισης (διατήρηση υψηλής ισχύος για μεγαλύτερο διάστημα).
Άβαταρ μέλους
By markvag
#904005 Συν το ότι έχει τα ίδια μοντέλα εδώ και... πολύ... υπερβολικά πολύ...

Μέχρι και οι Ευρωπαίοι έχουν αλλάξει μοντέλα, οι Κινέζοι αλλάζουν 3 γενιές μοντέλα στον χρόνο που χρειάζεται η Τέσλα να συμμαζέψει τις μ@λ@κίες που λέει ο τσέος της στο twitter.